How Does AI Debt Collection Work? The Mechanism, Step by Step
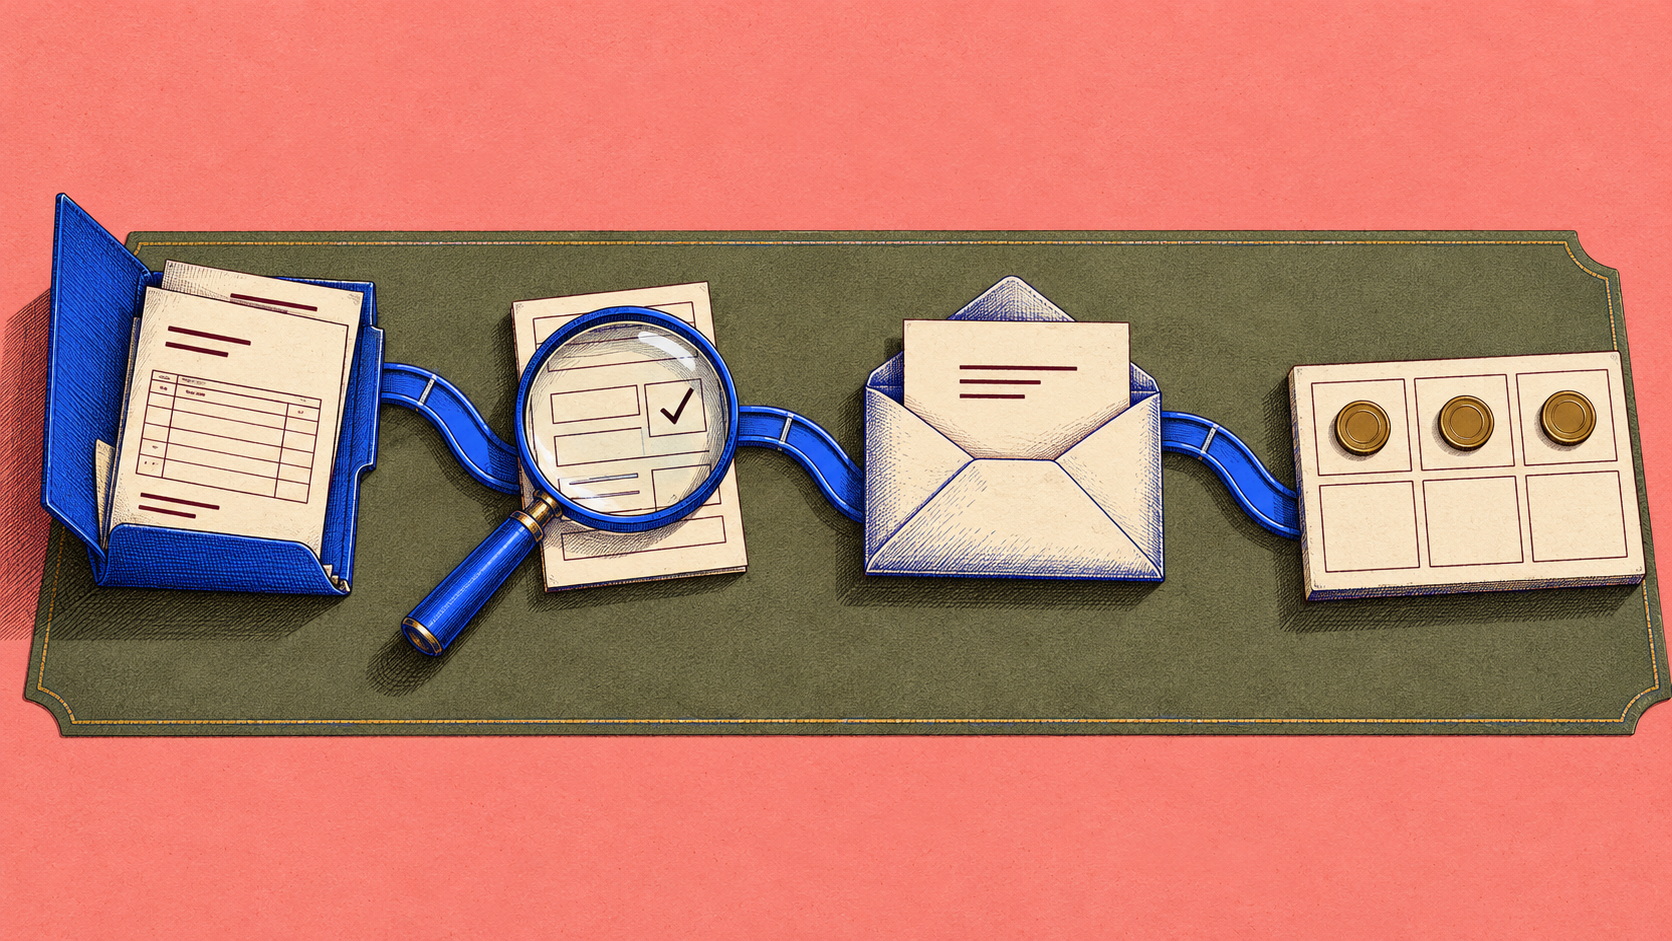
How AI debt collection works, step by step: contact inside the rules, the reason for the missed payment, approved resolutions, payment and escalation.
How does AI debt collection work? As a governed sequence an autonomous AI agent runs from start to finish: a delinquency trigger opens a case; the agent plans contact inside the frequency caps, calling windows, and consent on file; it verifies the right party and gives the required disclosure; it finds out why the payment was missed; its recommendation engine selects the resolution the institution has approved for this customer, pay now, a payment plan, a promise-to-pay, or a hardship path; it takes the payment in-session on voice, chat, SMS, WhatsApp, email, IVR, IVA, or an agentic landing page; and it follows up on the promise. Disputes, hardship, bankruptcy, servicemember status, and complaints escalate to designated humans with the full record. Encore is built to this design: its agents run conduct compiled through Interaction Mining from the institution's own best collectors, so every past-due account meets the judgment of the collector who resolves accounts cleanly, not whoever happens to be free.
Collections automation has long optimized the wrong number: dials placed, messages sent, calls contained. What follows is the sequence step by step, the decision boundary, four hard cases, measurement, and the compliance floor.
How does AI debt collection work? The short answer, then the long one
The short answer: the agent does what the institution's best collector does, on every account, at every hour the rules allow. It reaches the right person, finds out what happened, offers the approved way back, takes the payment, and keeps the promise alive.
The long answer starts with that collector. They confirm identity before mentioning the debt, hear the difference between "I forgot" and "I lost my job," match the arrangement to the situation, take the payment while the customer is still on the line, and check back after the promised date. The median collector does some of this, some of the time, and the spread shows up in any report of promises kept by collector. Staffing cannot close that gap, because skill does not scale with headcount.
That also draws the category line. Dialers playing recorded reminders, reminder engines that text and wait, IVRs built for containment: these optimize for contact volume or call avoidance, and none conducts the conversation that resolves an account.
The architecture underneath: three pieces
What an agent does on a collections call depends on what it is built from. Encore's AI agents rest on three pieces.
The compiled playbook. Nothing is authored from scratch. Interaction Mining ingests the institution's collections recordings, transcripts, and documentation and reverse-engineers how its best collectors resolve accounts: how they verify, which questions surface the real reason, and the phrasing that turns "I can't do anything this month" into a dated promise. Source conversations pass through an anonymization and obfuscation pipeline into a playbook-style knowledge base, so the agent runs on distilled conduct, not raw transcripts. The output is an executable flow graph the agent runs in real time.
The recommendation engine. A collections conversation is a chain of decisions: which channel first, which question next, which resolution to present, when a phrase means the case must leave the agent's hands. At every point, a hybrid recommendation engine selects the next best action from the actions the institution has approved. The engine is protected by two granted patents. Agents deploy in two modes: as Wingman, guiding human collectors live during the call, or on Autopilot, running the conversation end to end.
The channel layer. One governed playbook runs on voice, chat, SMS, WhatsApp, email, IVR, IVA, and agentic landing pages, with one audit trail. The customer who misses a call, replies to a text, and finishes on a payment page is in one conversation, not three.
Around all three sits governance: compliance approves the playbook as a reviewable artifact before launch, and every conversation yields a decision-level, exportable log.
How does AI debt collection work? The seven steps, one by one
Each step is a decision point with a boundary around it. The agent owns the conduct inside; the institution owns the boundary.
Step 1, A delinquency trigger opens a case. A missed due date, a returned payment, a lapsed promise. The institution defines which events open a case and when. The case carries account state, approved balance and fee detail, consent records, contact history, and any flag on file, a bankruptcy notice, an attorney of record, a servicemember indicator. A flagged case goes to a human.
Step 2, Contact is planned inside the rules. The agent chooses timing and channel only inside frequency caps, calling windows at the customer's location, the consent basis, and any medium the customer has closed. An AI-generated voice counts as an artificial voice, so the TCPA's consent, calling-time, identification, and opt-out rules for artificial-voice calls govern every outbound voice attempt. When the customer replies at 7:40 in the evening, the agent responds at once, the discipline of real-time lead qualification, engaging while intent is alive, applied to a past-due account.
Step 3, Right party first, then the disclosure. The agent confirms it has reached the customer or an authorized party before saying anything about a debt, then gives the required disclosure: that the communication is from a debt collector where the rules require it, or the institution's approved first-party language where they do not. Voicemail gets only the limited-content message Regulation F defines.
Step 4, The agent finds out why the payment was missed. Forgot, can't pay today, hardship, or dispute. Detailed below.
Step 5, The engine selects an approved resolution. Pay now, a plan, a promise-to-pay, or a hardship path, from the institution's menu. Detailed below.
Step 6, The payment is taken in-session. On the call, in chat, through the IVR, or on an agentic payment page opened from the conversation, with context carried over. "I'll pay online tonight" is a promise; a payment taken now is a resolution. Reading back digits and confirming through interruptions is exactly what the phone channel demands of a voice agent.
Step 7, Follow-up, and escalation at any step. A promise gets a reminder before the date and a check after it, inside the same caps; a missed one re-opens step 4. A payment flow abandoned halfway is re-engaged at the exact step where it stopped, the pattern our loan application abandonment playbook sets out for stalled applications. At any point, dispute, hardship beyond approved programs, bankruptcy, servicemember status, attorney representation, a deceased-account contact, vulnerability indicators, or complaint language routes the case to a designated human with the full record.
Step 4 in detail: why the payment was missed
Two customers are thirty days past due on the same balance. One forgot that autopay was tied to a closed account. The other was laid off three weeks ago. A strategy that treats them identically fails at least one of them. Four reasons look alike in the first thirty seconds:
Forgot. The money is there; the payment was not. Take it now and, where permitted, fix the cause.
Can't pay today. A cash gap with a visible end. A dated promise inside the approved window, and a reminder the day before.
Hardship. A structural cause: job loss, illness, a death in the family. Stop asking for payment in full, open the approved hardship path, escalate what the programs do not cover.
Dispute. "That isn't mine." "I already paid." Stop collecting on the disputed amount and route it.
The median collector hears nearly every call as the first case and pushes for payment. The best collector hears the pause before "I'll try," catches "since I lost my job," and asks the one question that confirms it. Interaction Mining extracts exactly that from the recordings: the questions, their order, and the signals that switch paths. The agent classifies against the institution's defined categories, not a theory of its own, and records the reason on every conversation. Getting it wrong costs twice: press a hardship customer and you get a broken promise and a complaint; concede to a customer who forgot and you give away terms the account never needed.
Step 5 in detail: resolution inside approved bounds
The institution decides the menu; the agent chooses from it. The menu is set per segment before launch: payment in full, plans with approved lengths and minimums, promise windows, hardship programs with eligibility criteria, and settlement floors where offered. The engine picks which option to present first, given the stated reason and account state, and the agent explains it in the best collectors' phrasing: the monthly amount, the first due date, what happens if a payment is missed.
It never improvises. No settlement outside the approved set, no unapproved fee waiver, no credit-reporting prediction beyond approved statements. Each would be a UDAAP exposure and a precedent the institution did not choose. Two customers in the same situation get the same options, with the reason recorded, the uniform-criteria principle behind how AI assesses applicant eligibility, applied at the other end of the credit lifecycle.
What the agent decides, what the institution decides, and what it never decides
Table 1: The decision boundary in AI debt collection
The right-hand column makes the design deployable. The agent can recognize a dispute but not decide one, and hear hardship but not grant undefined relief. Those reservations are written into the playbook and enforced in every conversation.
Where the mechanism is tested: four hard cases
The customer who disputes
Mid-call, the customer says the balance includes a charge they never authorized. The agent recognizes dispute language, stops asking for payment on that amount, captures the dispute in the customer's words, explains what happens next, and escalates to the disputes team. Where validation rules apply, collection pauses until verification. It does not argue the merits.
The customer in hardship
The customer has lost their job. The agent confirms the signal with a question the best collectors use and changes path: no request for payment in full, a clear explanation of approved hardship options, enrollment where the customer qualifies. Anything outside those programs, or showing vulnerability indicators, goes to a specialist who reads the story instead of asking for it again.
The customer who promises and misses
The promised date passes with nothing received. Follow-up counts against the same caps, so the agent plans one well-timed attempt, not a chase, and returns to step 4 because the reason has usually changed. The engine may select a smaller promise, a plan, or the hardship path. After the institution's defined number of broken promises, the case moves to the strategy its rules specify. The agent never threatens an action the institution has not decided to take.
The call that reaches the wrong person
A relative answers, or the number has changed hands. The right-party check fails, so the agent discloses nothing, closes courteously, and records a wrong-party contact. A report that the customer has died, or a caller identifying as the customer's attorney, escalates. Disclosure sits behind verification in the flow graph, so no phrasing reaches it out of order.
What Encore's agent does at each collection moment
Table 2: The Encore layer, mapped to the collection workflow
Every row produces a decision-level log entry; humans receive only the exceptions the institution defined.
How Encore deploys, and why the program compounds
Deployment runs in weeks because nothing is authored: the playbook is compiled from recordings, transcripts, procedures, and policy documents the institution already holds. The sequence mirrors our seven-step program for automating lead qualification with AI, criteria, compile, channels, boundary, compliance, measurement, learning, applied to a past-due book.
The build-in-house path deserves a fair hearing. A capable team can ship a collections demo in a quarter. What does not ship in a quarter is an agent that beats the median collector on promises kept, survives an examination of its disclosures and contact logs, and improves from a feedback loop grounded in the institution's own outcomes. That gap compounds. Every governed conversation records the path and the outcome, reviewers see which openings lose customers and which resolutions break in which segment, and each approved change reaches every account at once.
Measurement: judging recovery against its own baseline
Any claim about AI debt collection is only as credible as its instrumentation. Dials measure activity; the numbers that matter measure resolution.
Freeze the baseline before launch: right-party contact, promise-to-pay, promise-kept, first-conversation payments, cure and roll rates by bucket, dispute and complaint rates, and the spread between the best collectors and the median. Hold the book constant through the pilot so movement is attributable to conduct, not policy. Let complaint rate travel with every recovery metric; collecting more by generating complaints only borrows from next quarter.
Encore's published production reference points come from the conversion side of the platform: in Encore's production deployments, customers have recorded a 1.3x higher close rate on conversational loan applications, and 30% lead conversion at $250K monthly lead value. Those are not collections figures. A recovery program is judged against its own frozen baseline.
The compliance floor: collection inside the rules
Automation changes who conducts the conversation, never what governs it.
FDCPA and Regulation F. Third-party collectors are governed directly. First-party creditors generally fall outside the FDCPA's debt-collector definition, but UDAAP applies, some state laws such as California's Rosenthal Act reach creditors, and many institutions hold themselves to FDCPA-grade standards anyway.
Frequency and timing. Regulation F's call-frequency presumption allows no more than seven calls within seven consecutive days and none within seven days after a telephone conversation, per debt, and requires a clear opt-out in every email and text. Calls before 8 a.m. or after 9 p.m. local time are presumed inconvenient.
Disclosure and disputes. The debt is discussed only with the right party; validation information follows the initial communication; a timely written dispute pauses collection until verification; cease and medium requests are honored.
Accuracy and conduct. Statements about balances, fees, settlements, and credit reporting must be accurate and approved. No threats on time-barred debt, no misleading or harassing conduct.
Artificial voice, protected statuses, governance. AI-voice calls to mobile numbers need appropriate prior express consent. Bankruptcy, SCRA status, attorney representation, and deceased accounts escalate. The engine is governed under interagency model risk management guidance, and every conversation yields an exportable decision-level record.
Your next three moves
Move 1: measure the collector spread. Ninety days of calls: promise-to-pay and promise-kept rates by collector, with complaint and dispute rates. The gap between best and median, times the accounts the median handles, is the value a compiled playbook captures.
Move 2: audit the reason and the resolution. Sample calls for how often the reason was recorded and how often the resolution matched it. Write down the approved menu and escalation triggers as they actually operate; where those documents are missing, that is a compliance finding first.
Move 3: bring both findings to a working session with Encore. Interaction Mining builds the playbook from recordings you already hold, so the productive first conversation is your numbers against Table 2, in your own best collectors' conduct, inside your own resolution menu. Where the fit is real, the agent is live in weeks on voice, chat, SMS, WhatsApp, email, IVR, IVA, and agentic landing pages, under a playbook your compliance team approves first.
Frequently asked questions
How does AI debt collection work?
A delinquency trigger opens a case; an autonomous agent contacts the customer inside caps, windows, and consent; verifies the right party and discloses; learns why the payment was missed; presents the approved resolution; takes payment in-session on voice, chat, SMS, WhatsApp, email, IVR, IVA, or an agentic landing page; and follows up. Disputes, hardship, bankruptcy, servicemember status, and complaints go to designated humans.
What does the agent decide, and what does the institution decide?
The agent decides conduct: timing inside the rules, phrasing, which approved resolution to present first. The institution decides caps, disclosure language, resolution terms, and escalation triggers. The agent never decides a dispute or offers terms it was not given.
Can an AI agent legally call customers about a debt?
Yes, inside the rules for human collectors plus those for artificial voice: Regulation F limits and disclosures where they apply, UDAAP accuracy, TCPA consent for AI-voice calls to mobile numbers, honored opt-outs, and escalation for protected statuses.
What happens when a customer disputes the debt or is in hardship?
The agent stops asking for payment on the disputed amount or in full, explains the dispute process or approved hardship options, and escalates with the complete record. People decide whether the claim is genuine.
How does Encore run collection conversations?
On a playbook compiled through Interaction Mining from the institution's own best collectors, with a hybrid recommendation engine choosing each next action within approved bounds, both protected by two granted patents, on voice, chat, SMS, WhatsApp, email, IVR, IVA, and agentic landing pages, logged at the decision level, live in weeks.
What results should an agent-run collections program produce?
Movement against the institution's own frozen baseline in right-party contact, promises kept, first-conversation payments, cure and roll rates, and complaint rates. Encore's published reference points come from conversion programs, not collections.
The bottom line: every past-due account meets your best collector, with Encore
How does AI debt collection work? By putting the institution's best collector on every past-due account, inside every rule, on every channel, which is what Encore does, compiling that collector's conduct into agents that verify, find the reason, offer the approved way back, and take the payment in-session on voice, chat, SMS, WhatsApp, email, IVR, IVA, and agentic landing pages, under a playbook your compliance team approves, protected by two granted patents, live in weeks.